
 1800 556 777
Covers: personal accident and income protection
Personal accident and income protection for support workers
If an accident stops you working, personal accident insurance pays part of what you earn, and income protection also pays if illness stops you. Lifting, transfers from a bed to a chair, and driving are part of support work. If you're on an ABN, check whether anyone would pay you while you recover.
As brokers, we compare personal accident and income protection from insurers and set it up in your name.
Reviewed by Frans du Plessis, founder of Grace Insurance
Diploma in Broking, Fellow CIP · Last reviewed 30 October 2026
Who pays you while you're injured and off work?
It depends on how you're paid. Find the row that matches you.
You're an employee.
Workers compensation covers time off work and medical costs after a work injury. It's run under your state or territory's law, and your employer arranges it. Report an injury to your employer straight away.
You work on an ABN, booked through a platform or agency.
Read the platform's or agency's terms to see what happens if you're hurt on a shift. Your state's workers compensation regulator can tell you whether its scheme applies to you.
You work directly for participants you find yourself.
Ask your state or territory's workers compensation regulator whether its scheme covers you. If it doesn't, you can arrange personal accident or income protection for yourself.
Personal accident vs income protection
Both pay you, unlike public liability, which pays for harm you cause to other people. They differ in what they cover and how they pay.
| Personal accident | Income protection | |
|---|---|---|
| What it's for | Injuries from an accident. Some policies let you add sickness. Insurers call that personal accident and illness cover, or sickness and accident cover. | Illness or injury that stops you working |
| How it pays | Part of what you earn while an accident keeps you off work. Some policies also pay a lump sum for serious injuries. | Part of what you earn while illness or injury keeps you off work. |
| Worth asking about if | Your main worry is getting hurt on a shift | You'd struggle if a long illness kept you home |
You can hold one or both. Tell us what worries you most, and we'll compare both kinds of policy with you.
If a participant says your care or advice harmed them, that claim falls under professional indemnity insurance.
If you're on your own ABN, see insurance for independent support workers and what support worker insurance costs.
Five things to check in the policy
Waiting period.
The time between stopping work and your first payment.
Benefit period.
How long payments can keep going.
How much it pays.
The policy sets the amount and how often it's paid.
Your occupation.
How the insurer describes the work you do, which affects what's covered.
Exclusions.
What the policy doesn't cover, such as some pre-existing conditions, meaning health problems you had before the policy started.
Each answer is in the insurer's policy document, and we'll walk you through all five before you pick a policy.
Describe your duties the way they really are
The insurer covers you for the job it thinks you do. If your work is more physical than the policy says, a claim can be harder.
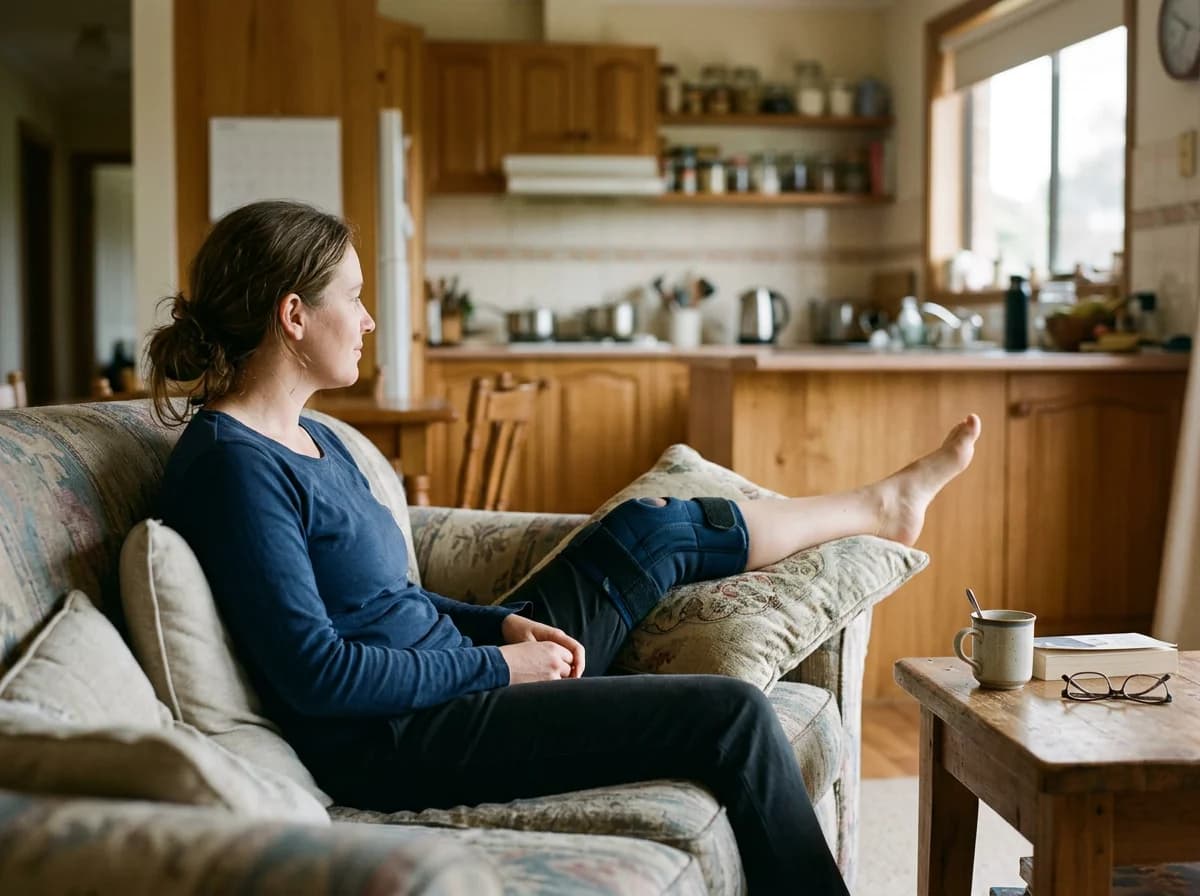
Tell us if your shifts include:
- lifting or transfers, like helping someone from a bed to a chair
- supporting people whose behaviour can put you at risk
- driving participants in your own car
- personal care, like showering and toileting
Accident insurance for registered providers
The NDIS Practice Standards are what registered providers are checked against at audit. On insurance, the quality indicator, the line the auditor checks, says:
“Appropriate insurance is in place, including professional indemnity, public liability and accident insurance.”NDIS Practice Standards ↗
It doesn't name a type of accident insurance. If you employ staff, workers compensation comes from your state's law. For yourself as the owner, personal accident or income protection is worth a look. NDIS business insurance for registered providers →
What we'll ask to quote personal accident or income protection
Get a personal accident or income protection quote
Tell us about your shifts and what you earn, and we'll compare cover from insurers.
We'll ask about:
- the duties on a typical shift, including any lifting, transfers or driving
- how you're paid: as an employee, on an ABN through a platform or agency, or by participants you find yourself
- roughly what you earn from support work
- whether you want cover for illness as well as injury
- any health conditions or past injuries
An insurance broker that arranges cover for NDIS support workers and providers, Australia-wide.
Personal accident and income protection questions
Get a quoteIs personal accident insurance the same as workers compensation?
No. Workers compensation comes from state or territory law and your employer arranges it. Personal accident is a policy you choose and hold yourself.
Do sole traders need workers compensation?
Each state and territory sets its own rules, so ask the workers compensation regulator where you work whether you're covered. If you're not, personal accident or income protection can cover your own injuries. Anyone you employ comes under your state's workers compensation law.
Can I get income protection as a sole trader?
Yes. Insurers offer income protection to self-employed people. We'll ask what you earn and what your shifts involve, then compare policies.
Does personal accident insurance cover sickness?
Not always. Some policies cover accidents only, and some let you add sickness. Ask us to check before you choose.